Selling a cooperative flat: the share, payment and tax
 Written and reviewed by Bc. Petr Kučera, MSc., MBA
When you sell a cooperative flat, you transfer a cooperative share. That share comprises the rights and obligations arising from membership of the cooperative, as defined by the Business Corporations Act. The buyer does not become the owner of the flat. If the share is tied to a lease, the buyer takes over the lease, or the right to conclude one, along with the rights and obligations that go with it. The legal basis is in Sections 595 and 736 of the Business Corporations Act (Act No. 90/2012 Coll.).
Delivery to the cooperative is what matters. Under Section 601(2) of the Business Corporations Act, the transfer takes effect in relation to the cooperative on delivery of an effective transfer agreement, unless the agreement specifies later effects. Delivery of a declaration by both parties confirming that they have concluded the agreement has the same effect. Signing alone may therefore be insufficient.
At GATSBYS, we recommend first identifying exactly what you are transferring, then checking the articles of association, membership and liabilities. Next, establish the buyer’s financing, align delivery, payment release and handover, and assess the tax position. This is our suggested approach, rather than a statutory sequence. Relevant provisions include Sections 601 and 736 of the Business Corporations Act and Sections 4 and 10 of the Income Tax Act. Our guide to selling a flat in Prague covers the wider process.
The information reflects the available data and legislation as at 9 November 2026.
We rely on the following versions: the Business Corporations Act as in force from 19 July 2024 (Section 595 and the following provisions), the Income Tax Act in its version for the period 1 August 2026 to 31 December 2026 (Section 4), the Cadastral Act (Act No. 256/2013 Coll.) as in force from 1 October 2025 (Sections 1 and 11 of the Cadastral Act) and the Civil Code (Act No. 89/2012 Coll.) as in force from 1 January 2026 (Section 559 and the following provisions of the Civil Code). The framework described here applies throughout the Czech Republic.
What are you actually transferring?
Cooperative share versus a flat in direct ownership
A flat in direct ownership is a unit registered in the Land Register (Cadastre of Real Estate). The difference between that and a share comes down to the exact subject of the agreement. We recommend the same precision in any materials prepared for buyers.
| Area | What it means for the cooperative share being transferred |
|---|---|
| Subject of the transaction | A membership share rather than ownership of a unit (Section 595 of the Business Corporations Act). |
| Use of the flat | Where the share is tied to a lease, the lease or the right to conclude a lease passes to the buyer, together with the related rights and obligations (Section 736(2) of the same Act). |
| Land Register | The share is transferred without any registration of the buyer’s ownership of the flat. You can still check who owns the building (Sections 1 and 11 of the Cadastral Act). |
| Loan security | Given the legal nature of the share, the buyer does not acquire ownership of the flat and cannot pledge it as their own property. This does not rule out other forms of financing (Sections 595 and 736 of the Business Corporations Act). |
Identifying the building’s owner does not settle the question. Section 729(2) of the Business Corporations Act also allows a cooperative flat to be located in a building owned by another person, subject to specific conditions. The tenant-member, or their legal predecessor, must have contributed to acquiring the flat through a membership contribution in cooperative construction under earlier legislation. The cooperative must also hold a right corresponding to an easement that secures the member’s use of the flat under the cooperative housing regime. Not every easement meets this condition.
Checks before you sell
Articles, membership, marital property and inheritance
The articles of association set out the cooperative’s rules. Under Section 736 of the Business Corporations Act, transferability cannot be excluded or restricted where the buyer meets the articles’ conditions for admission to the housing cooperative. We nevertheless recommend reviewing the articles: this statutory rule does not establish that every condition they contain is lawful.
We recommend finding out whether the share forms part of the community property of spouses (SJM). If it does, the law makes the spouses joint members. That does not produce a single signing rule that fits every married couple. Who deals with the cooperative does not, by itself, determine who is entitled to sell (Section 739 of the Business Corporations Act).
Under Section 737 of the Business Corporations Act, inheritance of a share also carries the tenancy or entitlement to enter into a lease under the applicable rules. A share belonging to SJM passes to the surviving spouse. We recommend assessing the individual property and inheritance circumstances to establish who may transfer it.
An expulsion challenged in court calls for particular care. According to Supreme Court case 27 Cdo 1674/2021, if a member facing expulsion files a timely application to have the expulsion decision declared invalid, the consequences of membership ending cannot be enforced against them until the proceedings end with a final decision. This does not confirm uninterrupted legal membership or establish that a transfer during the dispute carries no risk.
Debts, overpayments and the so-called anuita
Section 736(2) of the Business Corporations Act transfers relevant debts in both directions: the seller’s debts to the cooperative and the cooperative’s debts to the seller. They must relate to use of the cooperative flat or the entitlement to enter into a lease. The rule does not cover unrelated personal debts of the seller or automatically replace the cooperative with the buyer as borrower under a bank loan.
The seller remains a guarantor for debts attached to the share under Sections 601(1) and 736(3) of the Business Corporations Act. You may therefore have to pay a debt that has passed to the buyer. Neither signing nor physically handing over the flat automatically ends every associated risk.
Before signing, we recommend checking for arrears, overpayments and other liabilities, and agreeing with the buyer how any balance will be settled once the final statement arrives. Your private agreement with the buyer is distinct from the statutory transfer of liabilities and your guarantee obligations towards the cooperative. A payment confirmation cannot remove every subsequent risk. Sections 601 and 736 of the Business Corporations Act govern these relationships.
Knowing only that the cooperative calls an amount an anuita (often translated as ‘annuity’) does not tell you what it covers. The Business Corporations Act does not define the term. We recommend finding out which obligations it includes and what basis it has in the articles or in agreements (Section 736 of the same Act). The Supreme Court in 27 Cdo 1173/2022 distinguishes instalments of an additional membership contribution from contributions to a loan fund. Without the relevant documents, there is no way to say who the bank’s borrower is or what specific obligation the buyer takes on.
Cooperative transfer charges
The Business Corporations Act sets no uniform transfer fee, amount or payer. If the cooperative requests an administrative payment, we recommend checking its legal basis and payment rules. A demand alone does not establish entitlement to payment. Relevant authorities include Section 736 and Supreme Court case 27 ICdo 46/2022.
In 27 ICdo 46/2022, the Supreme Court found that, in that particular case, the buyers’ membership did not depend on paying a fee for updating the membership register. The decision does not determine whether administrative fees are generally permissible.
Supreme Court case 27 ICdo 46/2022 concerned a transfer governed by earlier legislation. In that context, the court accepted stricter requirements in the articles for the agreement’s form.
How the cooperative share transfer works
Form of the transfer agreement
The Business Corporations Act’s general rules do not require a written transfer agreement or a notarial deed, meaning a document drawn up by a notary. However, check the articles and contractual arrangements for specific requirements. Relevant provisions are Section 601 of that Act and Sections 559 and 560 of the Civil Code.
We recommend a written transfer agreement because it helps document the transaction and arrange delivery to the cooperative. This is practical advice, rather than a universal statutory requirement. The legal framework is Section 601 of the Business Corporations Act and Sections 559 and 560 of the Civil Code.
Key questions to resolve include:
- What conditions govern the agreement’s effectiveness, and when do its agreed legal effects begin?
- Who will prove delivery to the cooperative, and how?
- What documents are needed to release the purchase price?
- When will the flat be handed over, and under which rules?
These questions distinguish the transfer’s legal effects from contractual settlement arrangements, drawing on Section 601 of the Business Corporations Act and Supreme Court case 29 Cdo 4215/2016.
When the transfer takes effect and what to send to the cooperative
Under Section 601(2) of the Business Corporations Act, the transfer takes effect in relation to the cooperative when it receives an effective agreement, unless later effects are agreed. Delivery of both parties’ declaration confirming conclusion of the agreement has the same effect. Delivery does not remedy a failure to meet other requirements for a valid transfer.
We recommend obtaining clear evidence of delivery. Neither a lease drawn up later nor the speed of updates to internal membership records independently determines when the transfer occurs. Do not assume the buyer has become a member simply because the cooperative received some paperwork. See Section 601(2) of the Business Corporations Act and Supreme Court case 29 Cdo 4215/2016.
Escrow, payment release and handing over the flat
Escrow holds money for release once agreed conditions are met. The transfer takes effect in relation to the cooperative on delivery of an effective agreement, unless the agreement specifies later effects. Those effects do not depend on registration of the buyer’s ownership in the Land Register. See Section 601(2) of the Business Corporations Act and Supreme Court case 29 Cdo 4215/2016. We therefore recommend agreeing that proof of delivery of the agreement to the cooperative will serve as the basis for releasing the purchase price. Confirmation from the cooperative is one possible form of evidence.
We recommend aligning payment of the full purchase price into escrow, the transfer’s effects in relation to the cooperative, payment release and handover. The agreement determines the sequence. Section 601(2) of the Business Corporations Act imposes no universal requirement to release the money immediately upon delivery of the transfer agreement.
Drawing on the Ministry for Regional Development’s guidance on tenancy handovers, we recommend noting the meter readings on the day of handover, the number of keys, fittings and their condition, and any defects identified in the handover record. For a share transfer, a handover record provides practical evidence of handover. It is not a requirement imposed by the Business Corporations Act.
How can buyers finance a cooperative share?
Other property as security and further loan options
Security is an asset used to secure repayment of a loan. Published examples from lenders, such as Česká spořitelna, include borrowing against another property and interim financing where a future transfer into direct ownership is available. Selected unsecured purpose-specific loans may also be possible, such as the cooperative housing finance described by Česká spořitelna. Buyers may also use their own funds.
The share itself can be pledged subject to the conditions governing its transferability, although the articles may restrict or prohibit this. The lien arises through registration in the public register. See Sections 1320 to 1322 of the Civil Code and the Supreme Court’s collection of decisions. Legal eligibility for a pledge does not guarantee a bank will accept the share as mortgage security. Check the proposed arrangement with the provider; Česká spořitelna is one source of financing information.
According to the lender’s examples, other available security and the particular loan conditions may affect whether financing is available. The buyer’s income alone does not confirm approval for financing that share.
Financing the buyer’s purchase differs from repaying the seller’s mortgage. Our guide to selling a flat with a mortgage covers the latter and the associated steps.
When do LTV and CNB investment recommendations apply?
The Czech National Bank (CNB) defines LTV as the loan amount relative to the value of the property securing it. If another property secures financing for a share purchase, that property’s value is relevant. The same limits cannot be extended in this way to unsecured borrowing.
Distinguish legally binding limits from investment lending recommendations.
| Indicator | General binding limit | Investment mortgage recommendation |
|---|---|---|
| LTV | For consumer loans secured by residential property, a maximum of 80%. Applicants under 36 buying residential property for their own housing may borrow up to 90%. A 5% volume exemption applies (CNB). | CNB recommendation: a maximum of 70% from 1 April 2026 (CNB). |
| DTI | According to the CNB overview, the general binding cap is not active. | CNB recommendation: a maximum of 7 from 1 April 2026. |
| DSTI | According to the CNB overview, the general binding cap is not active. | No separate DSTI value for this investment recommendation is given here. |
In the CNB’s definitions, DTI compares the applicant’s total debt with income. DSTI compares debt service, meaning payments on obligations, with the applicant’s income.
According to the CNB, the investment recommendation concerns mortgages for a third or subsequent residential property, or for a property intended for letting. It is not a general statutory limit for everyone acquiring a cooperative share, nor does it promise financing.
The CNB’s practical procedures, dated 25 March 2026, count housing cooperative shares towards the number of residential properties owned for recommendations D and E. Their scope also includes loans to acquire a share that are secured on residential property and granted from 1 April 2026. This does not bring all unsecured loans within scope.
Tax when selling a cooperative share
The five-year test and its exceptions
A holding period test makes exemption conditional on how long an asset has been held. For an individual’s income from transferring a cooperative share, the period between acquisition and transfer must exceed 5 years, subject to statutory exceptions. A later sale of an owned unit is a different case. See Section 4(1)(q) of the Income Tax Act.
The five-year exemption is unavailable for a share acquired from business assets and transferred within 5 years after the relevant self-employed activity ends. It also excludes income received for a future transfer within 5 years of acquiring the share. A further specific rule addresses future transfers of shares from business assets. When the money is received therefore matters; this is not a general ban on advance payments. See Section 4(1)(q), points 1 to 3, of the Income Tax Act.
For an inherited share, the required holding period is reduced by the deceased’s evidenced period of ownership. The deceased is the person from whom you inherit. They must have been your spouse or a relative in the direct line, meaning an ancestor or descendant. The rule does not apply to every heir. See Section 4(1)(q) of the Income Tax Act.
According to the Financial Administration’s overview of tax changes, the former CZK 40 million exemption cap for individuals’ income from transfers of business interests meeting the holding period test was abolished from 1 January 2026. Each transaction still requires assessment against the exemption conditions.
Residence for tax purposes lasting 2 years does not, by itself, exempt a cooperative share transfer. Other statutory grounds for exemption remain available. See Section 4(1)(a), (q) and (s) of the Income Tax Act.
Own housing needs and the lease termination condition
Apart from the holding period test, the income may be exempt if you use the proceeds for your own housing needs. A further condition is that the lease connected with the transfer is terminated, and all other statutory rules must also be met. An intention to fund your own housing does not, by itself, guarantee the exemption (Section 4(1)(s) and Section 4b of the Income Tax Act).
A lease passing to the buyer is not the same as a lease being terminated. Under Section 736(2) of the Business Corporations Act, the lease passes together with the share. Section 4(1)(s) of the Income Tax Act, however, requires the lease to have been terminated. The Financial Administration’s historical statement from 2005 predates the Business Corporations Act, so whether the lease condition is met has to be assessed for each transaction.
Under Section 4b(2) of the Income Tax Act, the funds must be used for your own housing needs by the end of the following tax period at the latest. A tax period is the period relevant to assessing tax. Corresponding expenditure in the immediately preceding tax period may also qualify. We recommend establishing the actual deadline from your circumstances.
Reporting duties and non-exempt income
Where exemption depends on meeting your own housing needs, you must notify receipt of the funds by the tax return deadline for the year in which you received them. This is separate from the notification of exempt income triggered by its amount. See Section 4b(3) of the Income Tax Act.
According to the Financial Administration’s overview, an individual receiving exempt income exceeding CZK 5,000,000 from a cooperative share transfer must notify the tax authority by the tax return deadline for the year of receipt. The whole income counts, rather than just the profit. The published exception for property recorded in the Czech Land Register does not cover the share. See Section 38v of the Income Tax Act.
Income from a share transfer that is not exempt falls within ‘other income’ under Section 10 of the Income Tax Act. Further information is needed to determine the resulting tax or confirm which costs are deductible.
For a taxable share transfer, your own renovation costs for the cooperative flat cannot be deducted as an additional expense alongside the share’s acquisition cost. This conclusion concerns those renovation costs specifically and cannot be extended to other expenses generally. The authority is Supreme Administrative Court case 1 Afs 37/2023-30.
Should you transfer into direct ownership before selling?
We recommend comparing the specific timing, costs and conditions set by your cooperative. A transfer into direct ownership before sale and a sale of the share are different transactions. Their relative merits depend on your circumstances. See Sections 601 and 736 of the Business Corporations Act.
When you later sell an owned unit, earlier membership of the housing cooperative does not count towards the holding period for the flat itself. See Section 4(1)(b) of the Income Tax Act and Supreme Administrative Court case 2 Afs 211/2020-29. Other exemption routes require separate assessment, so a sale soon after transfer into direct ownership is not automatically taxable.
A later sale of an owned unit does not itself create the guarantee obligations attached to a cooperative share transfer. Previously incurred obligations do not automatically disappear, however. See Section 601(1) of the Business Corporations Act.
We recommend avoiding a fixed percentage adjustment when assessing price. In Supreme Court case 27 Cdo 1173/2022, the court stated that a share carrying a tenancy generally has a market value broadly comparable in scale to similar units in the same location.
The same decision, Supreme Court case 27 Cdo 1173/2022, addresses the settlement share: the financial settlement after membership ends. Its starting point is the share’s actual value on the date membership ends, allowing for obligations to pay the outstanding additional membership contribution and contribute to a loan fund. An unpaid contribution cannot automatically be deducted a second time from a value that already reflects it.
For more detail, see our article on how market price, price estimate and expert valuation report differ.
After the transfer and when to call a specialist
For later account reconciliations, we recommend following the agreed settlement rules. Keep the parties’ settlement arrangements separate from the seller’s guarantee obligations towards the cooperative: an agreement allocating costs does not itself end those obligations. See Sections 601 and 736 of the Business Corporations Act.
We recommend choosing a specialist according to the specific issue:
- Lawyer (attorney): consider legal advice for unclear articles, membership disputes, debts, ongoing expulsion, SJM, or uncertain contractual or payment-release conditions. This recommendation reflects the legal risks under Sections 601, 736 and 739 of the Business Corporations Act and Supreme Court case 27 Cdo 1674/2021.
- Notary: consider a notary where acquisition of the share through an estate, meaning the property left by someone who has died, is uncertain. The Notarial Chamber of the Czech Republic also describes notarial escrow for the purchase price. Neither that service description nor Section 737 of the Business Corporations Act establishes a general requirement to involve a notary.
- Tax adviser: consider advice where proceeds will fund your own housing, or where inheritance, business assets, income for a future transfer, disputed expenses or a subsequent unit sale are involved. The recommendation reflects the taxation and exemption conditions in Sections 4, 4b and 10 of the Income Tax Act and Supreme Administrative Court cases 1 Afs 37/2023-30 and 2 Afs 211/2020-29.
How GATSBYS can help with your sale
At GATSBYS, we are a Prague estate agency representing sellers of flats and villas exclusively in Prague.
We use data to prepare pricing and assess risks, then create the property’s written presentation, photographs and floor plan. Our marketing covers media planning, creative work, targeting and reporting. We manage the sale and enquiries, organise viewings and negotiate terms. When you sell through us, we coordinate the work of a law firm.
For more detail, see what estate agency commission covers and our explanation of brokerage agreements and exclusivity.
Expert commentary
My first priority would be to recognise that the sale concerns a membership share. Before publishing the listing, I would read the articles and check with the cooperative for possible transfer restrictions, related debts and overpayments.
When it comes to the money, I would keep a close eye on the order of the steps. The transfer takes effect in relation to the cooperative on delivery of the effective agreement, unless the agreement specifies later effects. In the agreement, I would state clearly who delivers it and on what conditions the money is released from escrow. If the buyer is borrowing, I would find out early what security their bank plans to take.
I would address tax before signing. The holding period test, your own housing needs and inheritance each have separate rules. Where anything is uncertain, I would recommend assessment by a tax adviser.
Petr Kučera, founder of GATSBYS
Frequently asked questions
Can the cooperative refuse a transfer if the buyer meets its membership conditions?
Where the buyer meets the articles’ conditions for admission to the housing cooperative, transferability cannot be excluded or restricted. The articles still need reviewing: this rule does not validate every condition they contain. See Section 736 of the Business Corporations Act.
When does the transfer take effect in relation to the cooperative?
Under Section 601(2) of the Business Corporations Act, this happens on delivery of an effective agreement, unless it specifies later effects. Delivery of a declaration from both seller and buyer confirming that they have concluded the agreement has the same effect. Signing alone may not suffice. Delivery does not replace the other requirements for a valid transfer.
Is the holding period test for a cooperative share 5 or 10 years?
For an individual’s income from transferring a cooperative share, the holding period exemption requires more than 5 years between acquisition and transfer. Exceptions cover business assets and income received for a future transfer. The agreement’s date alone may not provide enough information. See Section 4(1)(q) of the Income Tax Act.
Does 2 years of residence alone exempt a share sale?
No. Residence for tax purposes lasting 2 years does not by itself exempt a share transfer. Other statutory exemptions remain possible under Section 4(1)(a), (q) and (s) of the Income Tax Act.
Can the deceased’s ownership period count for an inherited share?
The five-year holding period test is reduced by the deceased’s proven ownership period if they were the heir’s spouse or a relative in the direct line. This does not cover every heir. See Section 4(1)(q) of the Income Tax Act.
Can I deduct my own renovation costs for the cooperative flat on top of the acquisition price?
For a taxable share transfer, your own renovation costs for the cooperative flat cannot be deducted in addition to the acquisition cost. Supreme Administrative Court case 1 Afs 37/2023-30 establishes this restriction; it does not exclude every other expense.
Does the Business Corporations Act generally require a written share transfer agreement?
The Business Corporations Act does not generally require a written agreement or a notarial deed. Specific requirements in the articles and contractual arrangements must still be checked. See Section 601 of that Act and Sections 559 and 560 of the Civil Code.
Does earlier cooperative membership count towards the holding period when selling an owned unit?
No. Earlier membership cannot count towards the unit’s ownership period. Other exemption grounds require separate assessment. See Section 4(1)(b) of the Income Tax Act and Supreme Administrative Court case 2 Afs 211/2020-29.
The Czech legal framework here reflects the legislation as at 9 November 2026, particularly Section 595 and subsequent provisions of the Business Corporations Act and Section 4 and subsequent provisions of the Income Tax Act. Have a lawyer assess your specific agreement and a tax adviser your individual tax situation. When you sell through us, we coordinate the law firm. Our guide to selling a flat in Prague explains the process and coordination.
Considering selling a flat or villa in Prague? Get in touch.
Request a sale assessment founder of GATSBYS
Selected for you
-
| Petr Kučera
Selling a flat in Prague
Selling a flat in Prague, from preparing documents to receiving payment: Land Register, escrow, PENB, SVJ confirmation, mortgage, tax and cooperative flats.
Read -
| Petr Kučera
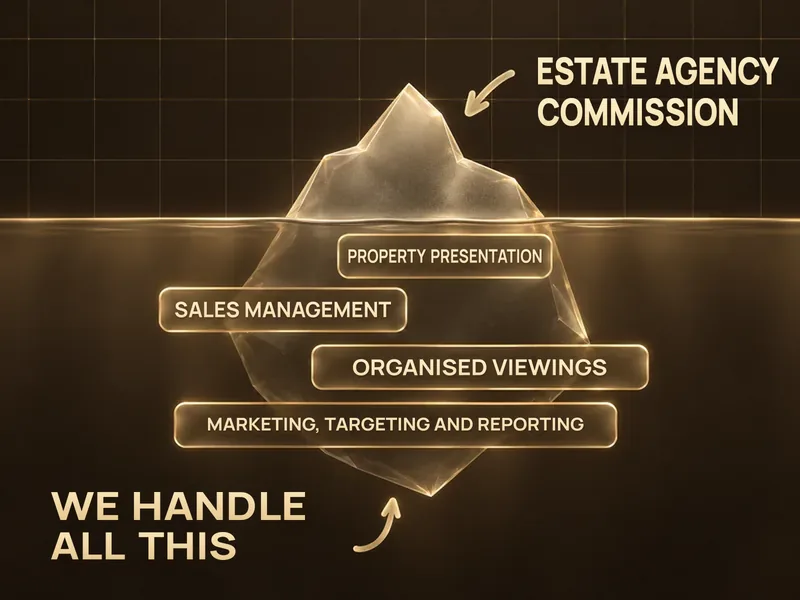
Estate agent commission: what you pay and what you get
Estate agent commission when selling a flat: understand VAT, included services and extra costs, then compare agency quotes by their final price and scope.
Read -
| Petr Kučera
Buy-to-let flat in Prague: yield, financing and what to check before you buy
Prague buy-to-let flats: gross yields from public data, how to work out your own net yield, CNB investment mortgage limits, tax and checks before you buy.
Read